What September’s sales measure
Developers sold 93.5% more new private homes in September than in August, and 16.1% more than a year earlier, according to URA’s monthly developers’-sales statistics. The count covers new private homes sold by developers, including completed and uncompleted properties. It excludes executive condominiums (ECs), which recorded a separate 23 sales.
These are monthly sales, not the number of homes available to buy. They also exclude resale transactions and measure a different aspect of the market from URA’s quarterly price index.
Projects already on sale remained active
Terra Hill in District 5 recorded 32 sales at a median S$2,209 per square foot, while The Sen recorded 25 at a median S$2,386 psf, according to URA’s monthly developers’-sales statistics. Both were already on the market. The reporting also identified Amberwood at Holland as September’s only newly launched project, with 24 sales from roughly 70 units released.
Fewer units launched over the first nine months
Developers launched 158 new private residential units in September, up 36.2% from August and 7.9 times the year-earlier figure. September itself therefore recorded an increase in releases, despite the smaller year-to-date total.
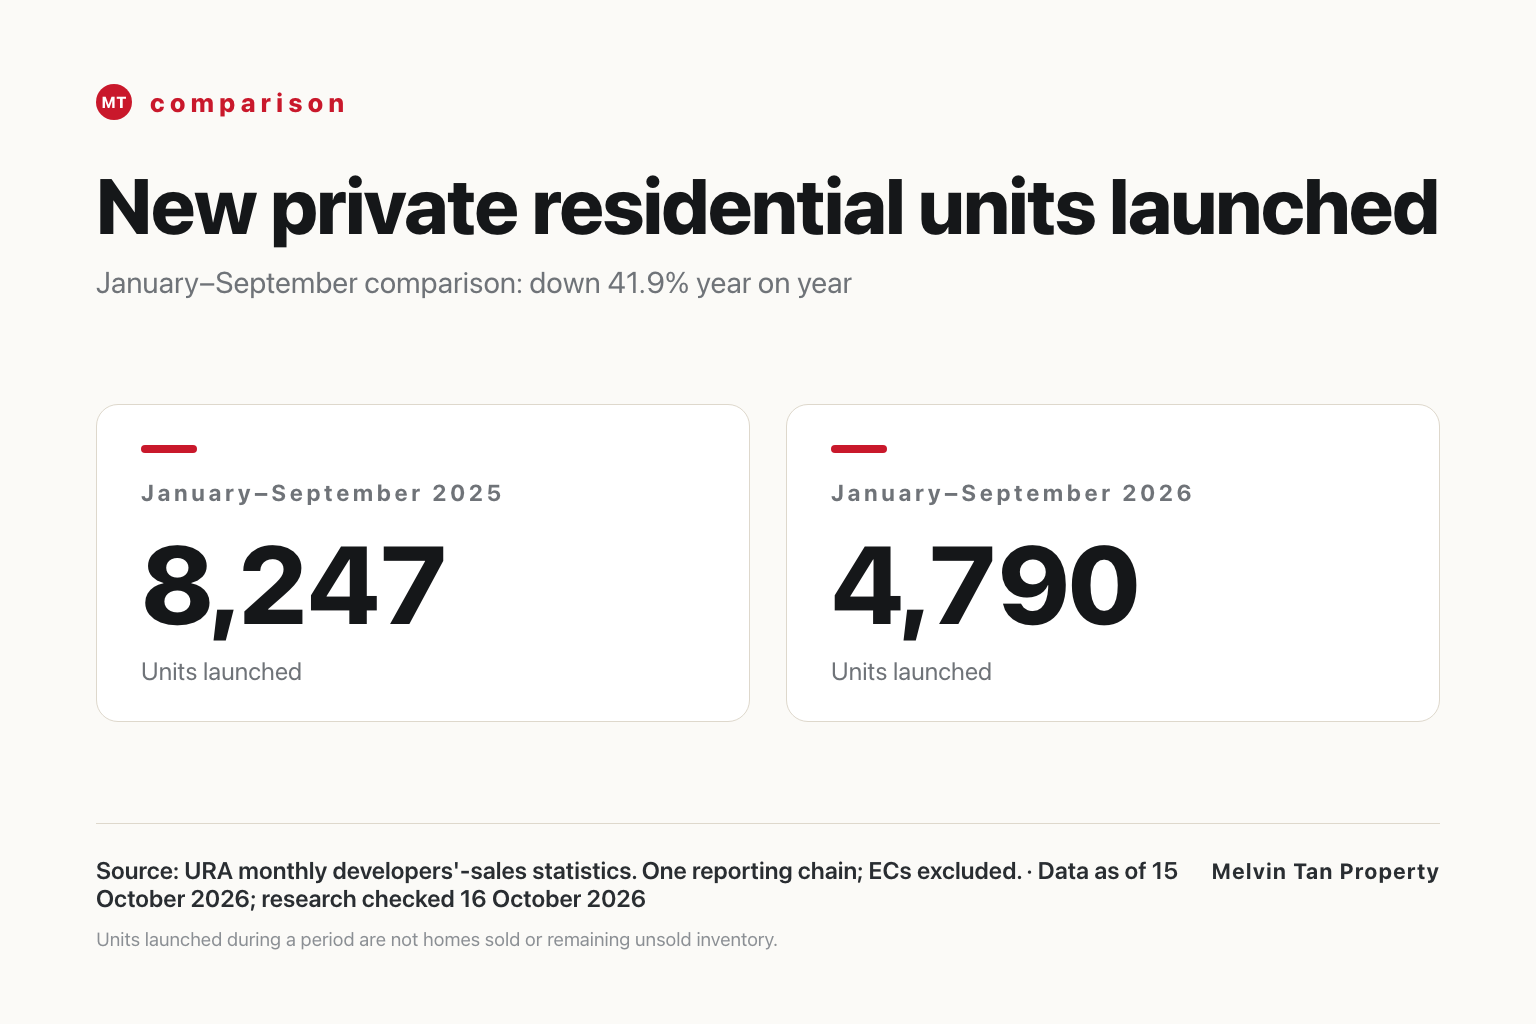
Across January–September, launches totalled 4,790 units, compared with 8,247 in the same period of 2025, a decline of 41.9%. Sales over those nine months were also lower: 5,334 units against 7,875 a year earlier.
Units launched during a period are not the same as unsold inventory at its end. Buyers can still purchase homes released in earlier months. The launch comparison alone cannot tell us how much choice remains, how many buyers are competing or whether a particular project will raise its prices.
What the rebound cannot establish
The large month-on-month sales increase needs to be read against August’s weak base. The supplied reporting also identifies the Hungry Ghost Festival period, from 13 August to 13 September, as relevant calendar context. It does not isolate that period’s effect on purchases or establish a broad recovery in demand.
Comparing a current offer with an upcoming launch
Start with the actual unit and its total purchase price. Compare total purchase price, floor area, layout, floor level, facing, tenure and expected completion. A project median summarises the units sold; it is not a valuation of the home you are considering. Ask for the current written price and the terms attached to any offer.
For a later launch, build the comparison around the household’s budget and moving date. Waiting may provide another option, but September’s sales figures cannot establish whether it will be cheaper or better suited to your needs.
As of 16 October, the pipeline reporting lists The Serra Residences at an estimated 133 units with an October window; Thomson Reserve at about 1,268 units, with reported starting prices around S$2,608 psf or S$1.544 million; and The Park Residence at about 43 units with a November/December window. It separately lists Wynwood Grand EC at about 430 units for December 2026 or January 2027. These are media-reported project estimates, indicative prices and launch windows, rather than confirmed availability or offers. Confirm current developer details before making a commitment.
For an owner considering a resale asking price nearby, developer offers are useful competing options to examine alongside comparable resale transactions.
The next useful checkpoint
23 October 2026 is the scheduled release date for URA’s full third-quarter statistics. Those figures can add broader market context, while confirmed project releases will show which planned buying options become available.
For a purchase decision today, put the current unit’s written offer beside the prospective project’s confirmed details and your financing and moving timetable. That comparison is more useful than treating a single month’s percentage change as a buying signal.
Sources and further reading
This article provides general educational information based on reported URA figures. It does not value an individual property, predict future prices or replace legal, tax, CPF, mortgage or financial advice. Confirm current developer details and verify the latest official figures before committing.