Quick answer
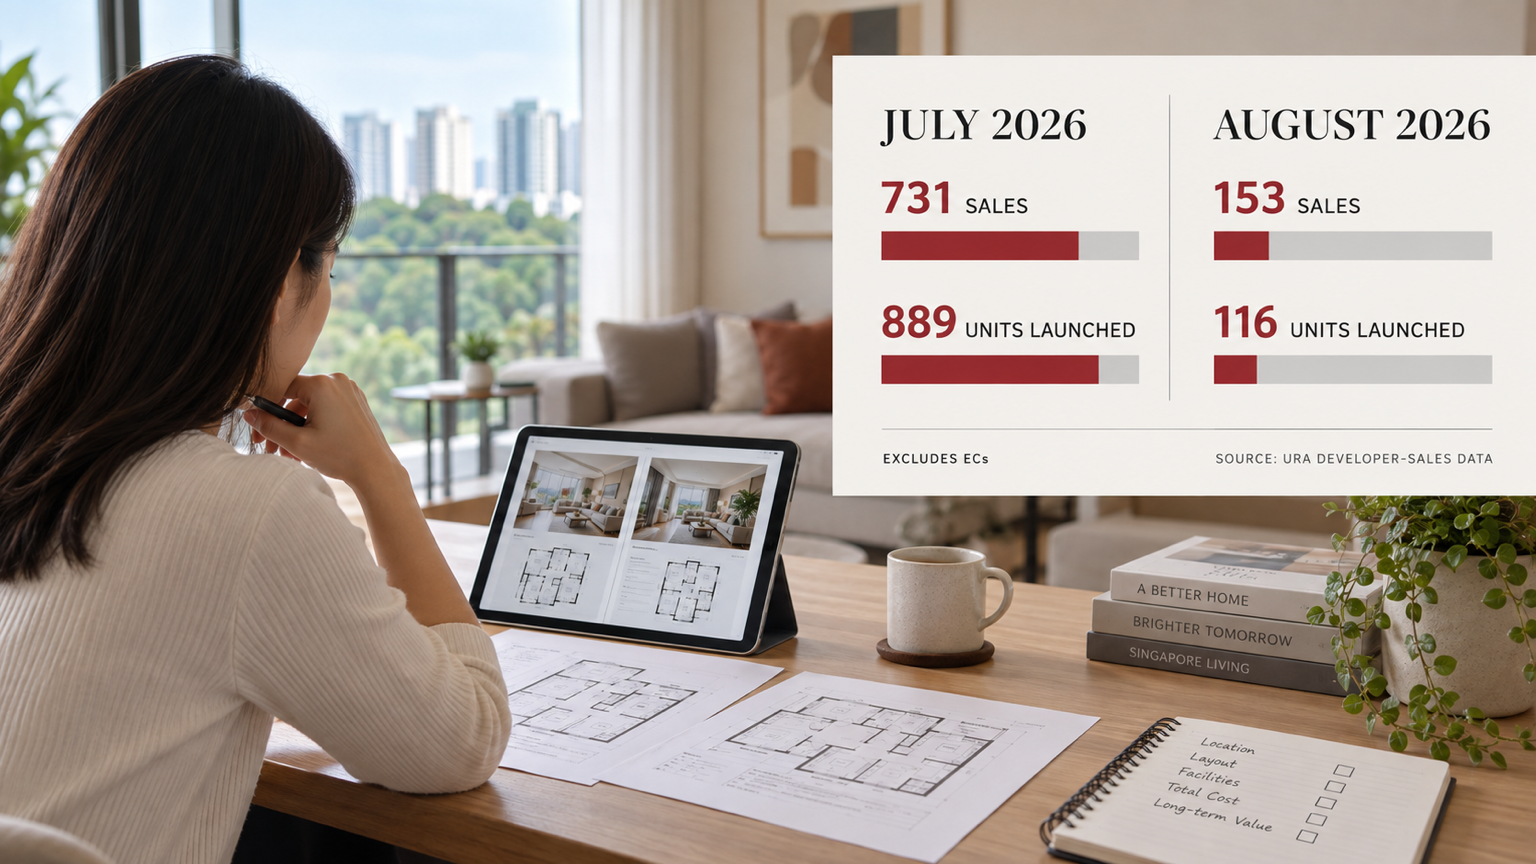
Singapore developers sold 153 new private homes in August 2026, excluding executive condominiums, after selling 731 in July. The sharp change coincided with a large reduction in homes launched: 116 in August compared with 889 in July.
For buyers, this is a reminder to read monthly sales together with launch supply and project mix. A national headline does not determine whether a particular project, unit or price fits the household.
Key takeaways
- URA’s developer-sales service was updated on 15 September 2026 with the preceding month’s information.
- Business Times and EdgeProp, citing URA, reported 153 new private-home sales excluding ECs in August, down from 731 in July.
- EdgeProp reported 116 units launched in August, compared with 889 in July.
- The change in monthly sales is not, by itself, proof of a broad change in demand or prices when launch supply also changes substantially.
- Buyers should compare project-specific sales, remaining units, total quantum, layouts, payment timing and resale alternatives.
- This statistical release did not change buyer eligibility, financing, CPF or stamp-duty requirements.
Background
URA’s Developers’ Sales service contains information supplied by licensed housing developers about units launched, sold and unsold. The number sold in the month is based on Options to Purchase issued by developers.
Monthly totals can vary sharply because new projects do not enter the market evenly. A month with major launches can record a large increase, while a month with little fresh supply can record much lower sales. Project size, location, pricing, unit mix and launch timing all affect the aggregate.
The earlier version of this Insight focused on July 2026, when Dunearn House and Lentor Gardens Residences entered the market. This revision adds August so readers can compare an active launch month with a month containing very little new supply.
Latest update
URA’s official service was last updated on 15 September 2026. Business Times and EdgeProp, both citing the URA release, reported that developers sold 153 new private homes in August excluding ECs. This was 79.1% below July’s 731 sales and 92.9% below the 2,142 sales recorded in August 2025.
EdgeProp reported 116 units launched in August, compared with 889 in July. Including ECs, 171 homes were sold in August. Business Times reported that sales excluding ECs totalled 5,038 units for the first eight months of 2026, about 34% below the corresponding 2025 period.
August had no major new condominium launch. EdgeProp reported that Dunearn House, Lentor Gardens Residences and The Sen were the three highest-selling private projects for the month, with 18, 15 and 12 sales respectively. These figures provide context, but they are not a ranking of investment quality or buyer suitability.
The reporting month is August 2026 and the data-release date is 15 September 2026. No separate effective date applies because this was a statistical release rather than a new rule.
July and August at a glance
| Month | Private homes sold | Units launched | Buyer context |
|---|---|---|---|
| July 2026 | 731 | 889 | Major project launches returned |
| August 2026 | 153 | 116 | No major new condominium launch |
Sales figures exclude ECs. Sources: URA developer-sales data, with aggregate context reported by Business Times and EdgeProp on 15 September 2026.
Who is affected
The update is relevant to buyers comparing current or upcoming new launches, HDB owners considering a move to private housing, owner-occupiers deciding between new launch and resale, and investors reviewing entry quantum and future competition.
It may also help private-property sellers understand the competing supply visible to buyers. Developer-sales data is not, however, a direct valuation of a resale home.
Who is not affected
The 153-unit figure excludes ECs. It also excludes private resale transactions and HDB resale transactions.
The release does not alter citizenship requirements, HDB or EC eligibility, loan assessment, CPF housing rules or applicable duties. Buyers must verify the requirements for their circumstances before committing.
What remains unchanged
A buyer still needs to review:
- a comfortable total budget and monthly commitment;
- available cash and CPF funds;
- loan eligibility and financing terms;
- applicable duties, legal fees and other acquisition costs;
- total purchase quantum rather than price per square foot alone;
- layout efficiency, facing, privacy and household fit;
- construction and progressive-payment timing;
- nearby resale choices and competing new launches;
- expected holding period and future buyer or tenant demand; and
- the effect of changes in interest rates, income or family needs.
No monthly sales figure guarantees future price growth, rental performance or resale demand.
Planning considerations
Read sales together with units launched
July and August demonstrate why the sales total should not be read alone. July contained substantial fresh supply and recorded 731 sales. August had only 116 units launched and recorded 153 sales.
This does not prove that every July project performed strongly or that demand disappeared in August. It shows that buyers had a different amount and mix of fresh stock available in each month.
Check the selected project, not only the national total
A national aggregate combines projects with different locations, tenures, prices, sizes and buyer profiles. Review how the selected project’s unit types are selling, which stacks remain, whether prices have changed and what alternatives are available.
Authorised balance-unit and price information should be rechecked at the time of decision. Availability can change after the monthly dataset closes. The Singapore New Launch project reviews provide a starting point for current comparisons.
Compare total quantum and usable layout
Price per square foot is one comparison measure, but it does not show the full funding commitment or how efficiently a home works for the household. Compare the purchase price, duties, legal costs, financing, layout, maintenance fees and likely renovation or furnishing needs.
Use the property affordability guide for the broad financing checks and the new-launch floor-plan guide to compare layouts systematically.
Compare nearby resale homes
A new launch offers a fresh lease, staged payments and early unit selection, but a resale home can offer immediate occupation, a completed environment and observable unit condition.
Compare usable space, maintenance fees, transport, schools, completion timing and total cost of ownership. The guide to New Launch versus resale condominiums sets out the practical differences.
Plan for payment timing
Buyers should understand when cash, CPF and loan disbursements may be required during construction. A comfortable purchase price can still create strain if payment timing, an existing mortgage or a delayed sale is not planned properly.
The progressive-payment guide explains the broad stages. Actual amounts and dates should be checked against the project documents and the buyer’s financing arrangements.
Avoid urgency based on one monthly headline
A low-sales month does not automatically create a bargain, just as a high-sales month does not prove that every remaining unit is attractive. Buyers should decide from verified project information and their own position rather than market-wide urgency.
FAQ
Sources
This article is for general educational discussion. Monthly market data does not determine whether a particular project or unit is suitable. Buyers should verify current URA information, authorised project materials, availability, pricing and the requirements applying to their circumstances, and obtain legal, tax or financial advice where required.