Quick answer
If you bought a subsidised HDB flat and now want to move to another subsidised home — a next HDB flat, or an EC from a developer — expect to pay a resale levy. If you are simply leaving the subsidised system (moving into a private condo or a resale flat purchased without any grant), there is no levy to budget for.
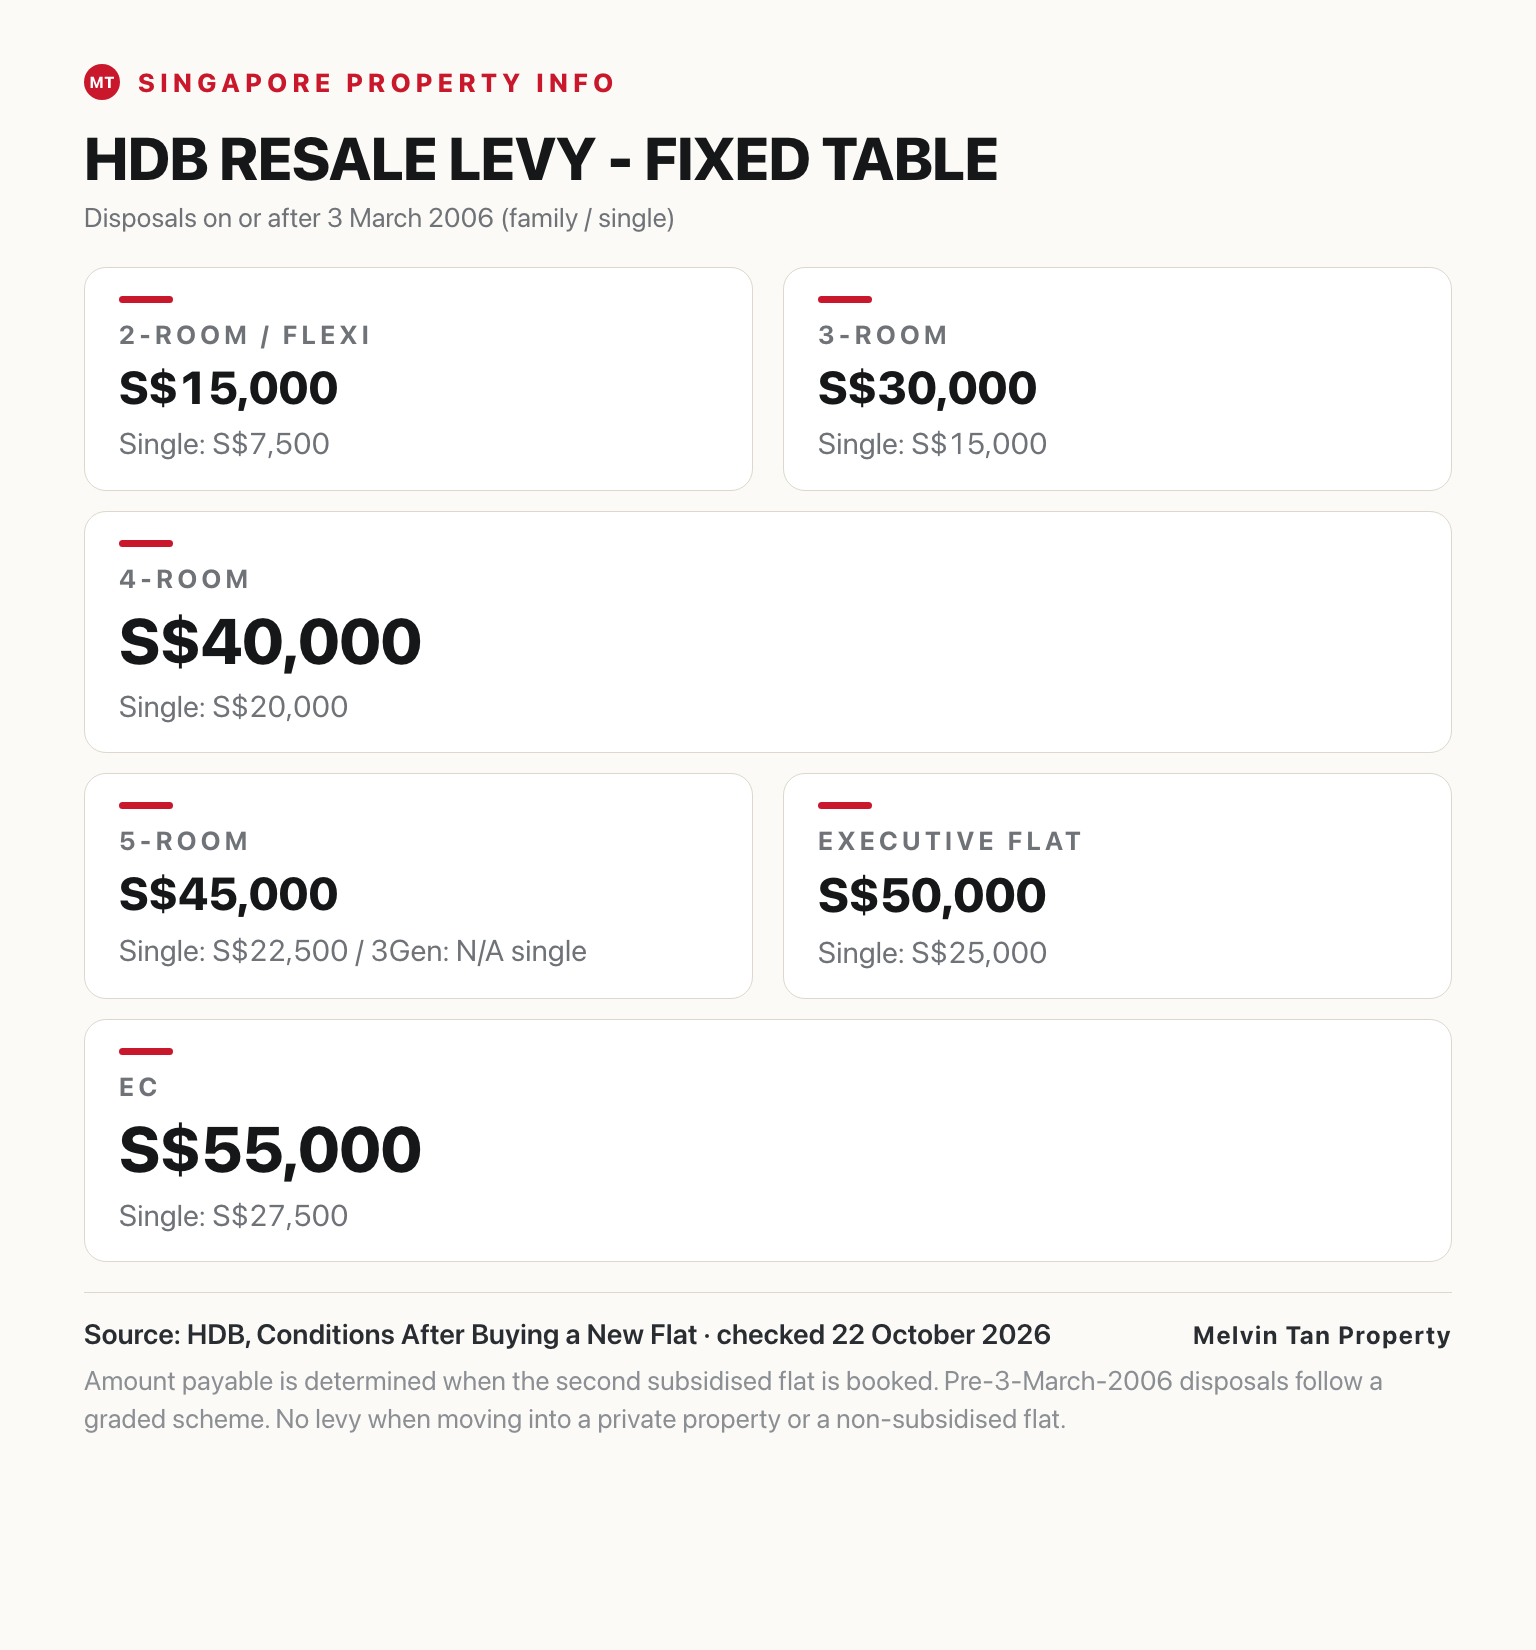
For disposals on or after 3 March 2006, HDB’s fixed table runs from S$15,000 to S$55,000 for families, depending on the subsidised home you give up; applicable single amounts are half. Earlier disposals use the graded calculation below. HDB determines the payable levy when you book the second subsidised flat.
What the resale levy actually is
HDB describes the levy as a mechanism to “reduce the housing subsidy of a second subsidised flat” so that subsidies are allocated more fairly among buyers. In plain terms: you benefited from a subsidy the first time around. If you choose to take a second subsidised purchase, the government recovers part of that earlier benefit at the point you commit to the new home.
Three points people regularly misread:
- It is not a capital-gains-style charge on your sale. Many owners hear “levy” and assume selling at a profit triggers it. It does not. The levy is tied to buying another subsidised home, not to the price you achieve when you sell or give up your flat.
- Leaving the system means no levy. HDB’s guidance states that if you do not intend to buy a second subsidised flat — “i.e., you are buying a resale flat or private residential property” — you need not pay the levy. Note the nuance: buying a non-subsidised resale flat (one you fund at market price without a grant) does not attract the levy; a subsidised next flat does.
- ECs count as subsidised. HDB explicitly treats units sold by developers under the EC scheme as subsidised housing, because their prices are set below comparable private stock. An upgrader who sells a 4-room HDB flat and buys an EC should still plan for the levy.
What to budget: HDB’s levy table
For anyone whose first subsidised flat was disposed of on or after 3 March 2006, HDB publishes fixed amounts by the type of flat you are giving up:
Fixed levy amounts by flat type disposed of
| First subsidised flat you dispose of | Buy next home as a family | Buy next home as a single |
|---|---|---|
| 2-room / 2-room Flexi | S$15,000 | S$7,500 |
| 3-room | S$30,000 | S$15,000 |
| 4-room | S$40,000 | S$20,000 |
| 5-room | S$45,000 | S$22,500 |
| 3Gen | S$45,000 | Not applicable |
| Executive flat | S$50,000 | S$25,000 |
| Executive Condominium (EC) | S$55,000 | S$27,500 |
Source: HDB’s fixed resale levy table, as published on HDB’s Conditions After Buying pages, checked 22 October 2026.
The EC amount is the row for the subsidised home you dispose of, not a surcharge simply for choosing an EC next. HDB’s EC guidance specifies the applicable grant/project conditions; confirm that your EC history falls within them.
If your first subsidised flat was sold before 3 March 2006, a graded percentage scheme applies instead, calculated on the higher of the sale price or 90% of market value — 10% for 2-room sellers buying a larger flat type, otherwise 15% (5% and 7.5% respectively for singles), 20% for 3-room, 22.5% for 4-room, and 25% for 5-room and Executive flats (half for singles) — subject to minimum amounts equal to the HDB-flat rows in the fixed table above (up to S$50,000 for an Executive flat).
Two household-specific factors can still shift your own number: whether you are listed as core applicant or core occupier, and — for Plus and Prime flats — the separate subsidy recovery rule, which requires returning a percentage of the sale price or valuation when you sell one of those flats. HDB notes this recovery sits on top of any resale levy, and that the exact percentage is announced when each Plus/Prime project is launched.
When — and how — the levy is paid
HDB determines your payable levy at the point you book your second subsidised flat, regardless of how you hold the ownership interest. Payment must come from cash and/or your flat sale proceeds; it cannot be added to a housing loan.
When the levy is settled
| Your timing | How the levy is settled |
|---|---|
| You dispose of your first subsidised flat before key collection of the new flat | The levy must be paid in cash at key collection — you cannot wait for sale proceeds to arrive |
| You dispose of your first subsidised flat after key collection | The levy is deducted from your net sale proceeds when the old flat sells; any shortfall must be covered in cash |
Source: HDB payment-of-levy guidance, checked 22 October 2026.
The relevant question is whether you dispose of the first flat before or after collecting the next flat’s keys. Use the table above to plan the payment source and timing, and see our step-by-step account of how a private-property purchase timeline sequences the offer, financing checks and completion milestones around exactly this kind of transition.
Where the levy fits in an upgrading plan
If you are weighing your options after your MOP is done, our broader guide to upgrading from an HDB flat to an EC walks through the whole decision — this article is the costing slice of that picture. Three practical reminders when you build the budget:
- Budget the levy before anything else. It is a committed, cash-only line item that comes off the top of your planning, and your CPF refund from the sale is a different, later event in the proceeds sequence — don’t net one against the other in your head.
- Treat the flat-type table as planning numbers, not quotations. Owners sometimes ask which unit types keep them levy-free; the honest answer, from HDB’s own table, is none — the amount depends on what you’re giving up, and HDB determines the payable amount when you book the second subsidised flat.
- Sequence matters. If you are shortlisting candidates post-MOP, our post-MOP shortlisting guide shows where financing confirmations land relative to booking deadlines, so the levy figure you’re carrying gets checked against real cash positions, not optimistic ones.
If you are weighing an EC upgrade, plan your move with Melvin to review your levy exposure, financing position and next-home timeline before committing.
FAQ
Official sources
- Housing & Development Board — Conditions After Buying a New Flat — official guidance accessed 22 October 2026
- Housing & Development Board — Conditions After Buying a Resale Flat — official guidance accessed 22 October 2026
- Housing & Development Board — Conditions After Buying an Executive Condominium — levy applicability and amounts checked 22 October 2026
- Housing & Development Board — full indexed levy-table source checked 22 October 2026
This article provides general educational information based on HDB’s published guidance. Individual levy outcomes depend on being listed as core applicant/core occupier in the flat application — households should confirm their own status with HDB before relying on the general table. It does not value an individual property or replace legal, tax, CPF, mortgage or financial advice.